UAE E-Invoicing Penalties: the Fines, the AED 50,000 Cap and How to Avoid Them
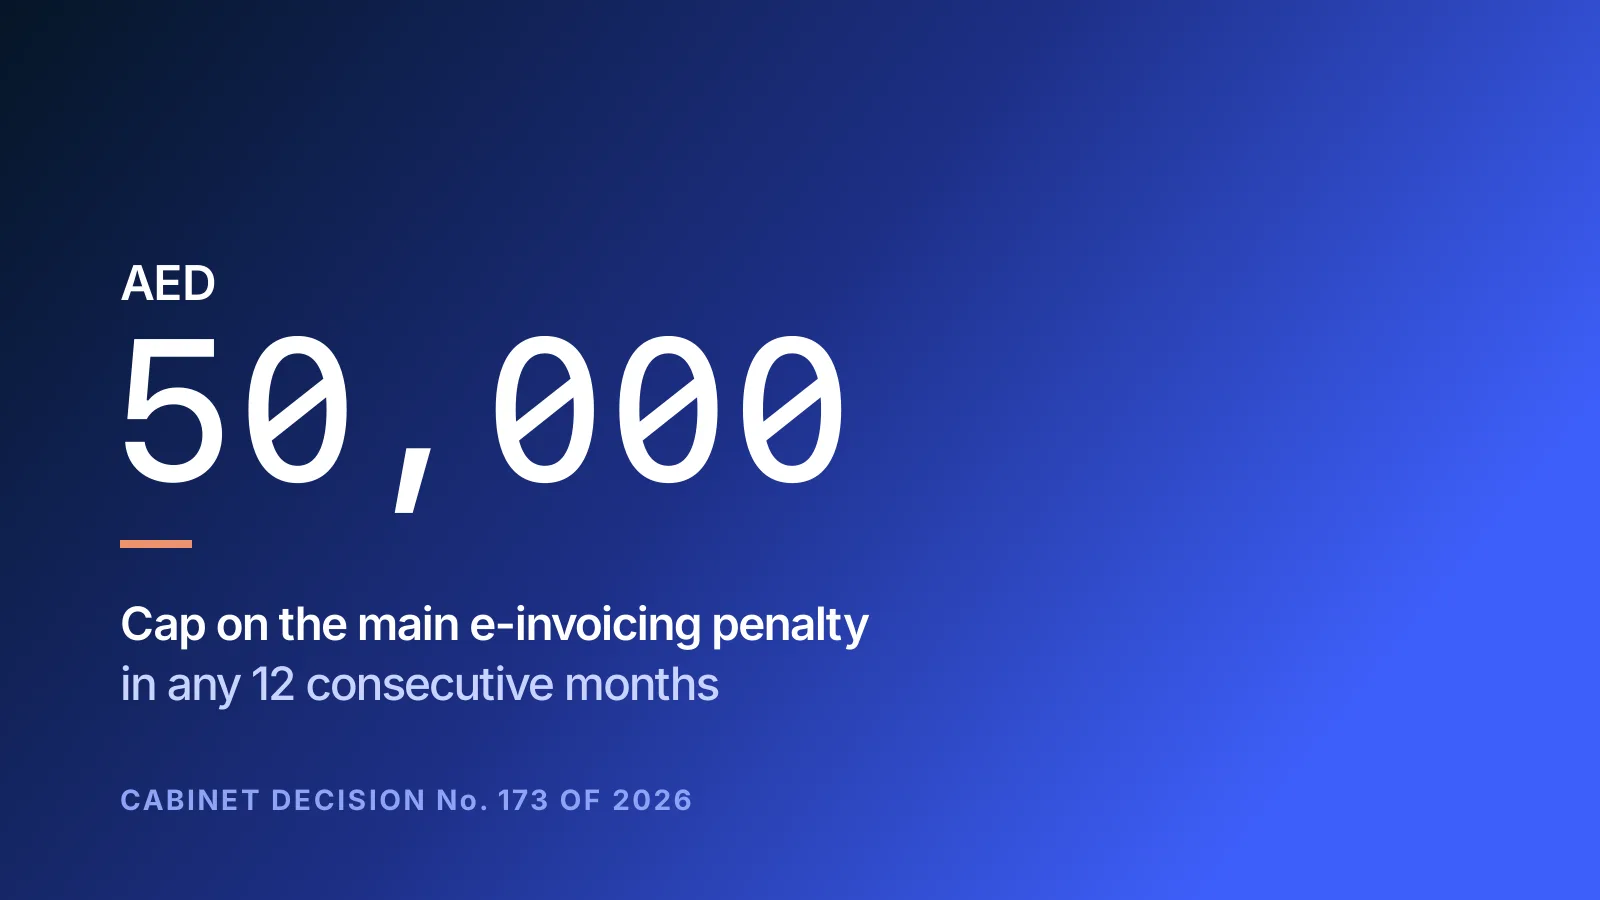
Cabinet Decision No. 173 of 2026 sets four e-invoicing penalties. The largest one, for not implementing the system or not appointing a provider, is AED 5,000 for the first violation and AED 5,000 for every further month, with a ceiling of AED 50,000 in any 12 consecutive months.
The Ministry of Finance announced the decision on 30 October 2026. It repeals Cabinet Decision No. 106 of 2025, which had set the first e-invoicing penalty table a year earlier, and takes effect from the day after its publication in the Official Gazette (Article 5). This guide goes through each penalty in the new table: who pays it, how it is counted and what stops it from arising.
Who is exposed
The decision applies to two parties, and both are defined in Article 1.
- The issuer is any person obliged to issue, transmit, share and exchange e-invoices and e-credit notes through the Electronic Invoicing System.
- The recipient is any person who must receive e-invoices and e-credit notes through the system.
Most businesses are both: they issue invoices to customers and receive invoices from suppliers. The system covers B2B and B2G transactions, and both sides of a transaction need their own Accredited Service Provider (ASP).
Businesses that use e-invoicing voluntarily are outside the decision. Article 2(2) excludes any person who issues, transmits, shares, exchanges or reports e-invoices and e-credit notes on a voluntary basis. Since 1 July 2026 any business can join early, and doing so carries no penalty risk until its own phase becomes mandatory.
Not implementing the system
Item 1 of the table annexed to the decision covers two violations:
- The issuer or the recipient fails to implement the Electronic Invoicing System under Ministerial Decision No. 244 of 2025, including failing to appoint an ASP.
- A recipient that has implemented the system then fails to keep meeting its obligations as a recipient under Ministerial Decision No. 243 of 2025.
The penalty is the same for both: AED 5,000 for the first violation, then AED 5,000 for each month or part of a month during which the non-compliance continues. The total may not exceed AED 50,000 within any 12 consecutive months.
| Months of non-compliance after the first violation | Total penalty |
|---|---|
| 0 (first violation only) | AED 5,000 |
| 3 | AED 20,000 |
| 6 | AED 35,000 |
| 9 or more, within 12 months | AED 50,000 (cap) |
A part of a month counts as a full month. A business whose ASP deadline passed on 30 October 2026 and which appoints a provider in mid-December has two months of continuing non-compliance on top of the first violation.
Under Cabinet Decision No. 106 of 2025 this penalty was AED 5,000 a month with no ceiling and applied to issuers only. The new decision adds the cap and extends the penalty to recipients.
Missing e-invoices and credit notes
Items 2 and 3 of the table cover documents that the issuer does not issue and transmit to the recipient through the system:
- e-invoices: AED 100 for each e-invoice, up to AED 5,000 per calendar month;
- e-credit notes: AED 100 for each e-credit note, up to AED 5,000 per calendar month.
The two caps are separate. A business that misses 70 e-invoices in one month pays AED 5,000, not AED 7,000. If it also misses 10 e-credit notes that month, those add AED 1,000.
An e-invoice or e-credit note has to go through the system within 14 days of the transaction (the earlier of the supply date and the payment date), and a VAT-registered business must also meet the deadline in the VAT law. A credit note is required when a transaction is cancelled, the agreed price falls, a payment is refunded in full or in part, or an invoice contained an administrative or numerical error.
Not updating your ASP data
When the data your business has registered with the Federal Tax Authority changes, for example its trade name or address, you must tell your ASP in writing within 5 business days of the FTA confirming the change. Item 4 of the table sets the penalty for missing that deadline: AED 250 for each day of delay or part of a day, up to AED 5,000 per calendar month. It applies to issuers and recipients alike.
The old decision charged AED 1,000 a day for the same failure, with no monthly limit. A delay of 30 days in one month now costs AED 5,000 at most.
One violation, one penalty
Article 3(2) prevents double counting. If the same person acts as issuer, recipient or both in respect of the same violation, only one administrative penalty is imposed for that violation. A business that has implemented e-invoicing neither as issuer nor as recipient pays a single penalty under item 1.
What changed from Cabinet Decision 106/2025
| Violation | Cabinet Decision 106/2025 | Cabinet Decision 173/2026 |
|---|---|---|
| System not implemented, ASP not appointed | AED 5,000 per month, no cap, issuer only | AED 5,000 first violation + AED 5,000 per month, cap AED 50,000 in 12 months, issuer and recipient |
| Recipient stops meeting its obligations | Not covered | Same scale and cap as above |
| E-invoice not issued and transmitted | AED 100 each, up to AED 5,000 per month | Unchanged |
| E-credit note not issued and transmitted | AED 100 each, up to AED 5,000 per month | Unchanged |
| ASP not told about a data change | AED 1,000 per day | AED 250 per day, up to AED 5,000 per month |
| FTA not told about a system failure | AED 1,000 per day | Removed |
The Ministry of Finance confirmed in its announcement that the penalty for failing to notify the Authority of a system failure has been removed. The duty itself remains: issuers and recipients still tell the FTA about a failure of the e-invoicing system within 2 business days. Missing that deadline simply no longer carries its own fine under the new table.
When it applies
Penalties start for each business on the date its phase becomes mandatory. Ministerial Decision No. 244 of 2025, as amended, sets the phases, and the Ministry of Finance’s e-invoicing guidelines (version 2.0, 26 October 2026) repeat them:
| Who | Appoint an ASP by | E-invoicing from |
|---|---|---|
| Annual revenue of AED 50 million or more | 30 October 2026 | 1 January 2027 |
| Annual revenue under AED 50 million | 31 March 2027 | 1 July 2027 |
| Government entities | 31 March 2027 | 1 October 2027 |
Revenue is measured from the financial statements of the most recent accounting period. A business with AED 50 million or more that has not appointed an ASP is already late: its first violation under item 1 arose after 30 October 2026, and every further month adds AED 5,000 until the cap.
How to stay clear
- Find your phase in the table above and put both dates in your compliance calendar.
- Appoint an accredited ASP before your deadline. The Ministry of Finance publishes the list of accredited providers. See our guide to choosing an ASP.
- Make sure you can receive e-invoices as well as send them. Item 1 covers recipients too.
- Check that your invoices can be produced in the PINT AE format your ASP will transmit. Our PINT AE and Peppol explainer covers what the format needs.
- Set up a routine for credit notes, so that every cancellation, price change or refund produces an e-credit note within the deadline.
- When your trade name, address or other FTA registration details change, tell your ASP within 5 business days of the FTA’s confirmation.
- Keep a written procedure for system failures, including the 2-business-day notice to the FTA, even though missing it no longer has its own fine.
The e-invoicing readiness checklist turns these steps into a full preparation plan. For the dates and the wider rollout, see the SME guide to UAE e-invoicing. Penalties for VAT and tax procedure violations are a separate regime: see the 2026 tax penalty regime under Cabinet Decision 129 and VAT penalties and deadlines.
What this means for you
Cabinet Decision 173 of 2026 makes the e-invoicing penalties smaller and predictable, but it does not change the deadlines. Three things to act on:
Know your phase and your two dates
Businesses with AED 50 million or more had to appoint an ASP by 30 October 2026; everyone else has until 31 March 2027. Each month late on item 1 adds AED 5,000 until the AED 50,000 cap.
Cover both sides of the network
The penalty for not implementing the system now applies to recipients too. You need to be able to receive e-invoices through your ASP, not only send them.
Keep the small obligations on a routine
Missing e-invoices and credit notes are counted per document, and ASP data changes per day. A credit-note routine and a 5-business-day rule for registration changes keep both at zero.
Frequently asked questions
What is the maximum e-invoicing fine in a year?
For not implementing the system or not appointing an ASP, AED 50,000 within any 12 consecutive months: AED 5,000 for the first violation and AED 5,000 for each further month until the cap (Cabinet Decision 173 of 2026, annexed table, item 1).
How much is the fine for a missing e-invoice?
AED 100 for each e-invoice not issued and transmitted through the system, up to AED 5,000 per calendar month. E-credit notes have the same amount and a separate AED 5,000 monthly cap (items 2 and 3).
What is the fine for not telling my ASP about a change in my data?
AED 250 for each day of delay or part of a day, up to AED 5,000 per calendar month (item 4). The notice is due within 5 business days of the FTA confirming the change.
Can I be fined twice as both issuer and recipient?
No. Where the same person acts as issuer, recipient or both in respect of the same violation, only one administrative penalty is imposed for it (Article 3(2)).
Do businesses that use e-invoicing voluntarily pay penalties?
No. Article 2(2) excludes anyone who issues, transmits, shares, exchanges or reports e-invoices and e-credit notes on a voluntary basis, so a business that joins before its phase becomes mandatory carries no penalty risk.